More withdrawals. More questions.
A client is drawing more from their RRIF or investments to cover expenses. You want to examine the tax implications and how long that approach can continue.
For Financial Planners, Accountants & their retired clients
When a client’s retirement income isn’t stretching far enough, the next withdrawal or new loan deserves a closer look.
I help you explore whether home equity belongs in the conversation, alongside the tax and financial planning advice you already provide.
Start with a general scenario. No client names or financial documents needed.
A second opinion focused on the person, the options and the longer-term cost.
Sharon Patton · Mortgage Broker
Certified Canadian Reverse Mortgage Consultant · CCRMC ID 5131-5933-7618
When another perspective helps
Some clients have built substantial equity in their home but still feel squeezed each month. These are useful moments to pause and compare the choices.
A client is drawing more from their RRIF or investments to cover expenses. You want to examine the tax implications and how long that approach can continue.
Mortgage or line-of-credit payments are putting pressure on a fixed income. A lower monthly outflow may help, but the total cost still matters.
Your client wants to understand their options before selling investments, taking on more debt or making a decision about their home.
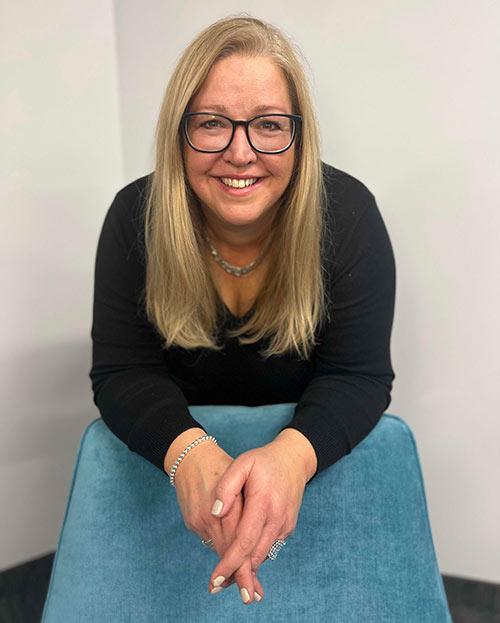
A conversation with Sharon
“I don’t approach this as a product discussion. I look at whether using home equity improves a client’s after-tax cash flow and overall financial position — or whether the alternatives are more efficient.”
My role is to explain the mortgage options and their costs. Your investment and tax expertise helps put those options in context, so the client can make a more informed decision.
Sharon Patton
Mortgage Broker · Burlington, Ontario
Let’s talk through a scenario →
Compare the whole picture
The interest rate matters. So do cash flow, tax implications, remaining equity and the client’s plans for the years ahead.
| Option to review | Questions worth asking together |
|---|---|
| RRIF withdrawals | What would additional withdrawals mean for the client’s tax position and remaining retirement savings? The accountant assesses the tax impact. |
| Selling investments | What are the account-specific tax consequences, market timing considerations and effects on the client’s longer-term plan? |
| HELOC or mortgage | Can the client qualify and comfortably carry the required payments? How would changing rates affect their budget? |
| Reverse mortgage | Would payment flexibility justify the interest, fees and effect on remaining equity? What happens if the client moves or repays early? |
| Downsizing or keeping the current plan | Would a move, spending adjustment or existing approach better support the client’s priorities without adding borrowing costs? |
A straightforward next step
Start with the pressure point: rising withdrawals, ongoing debt payments or a gap between income and expenses.
We discuss borrowing costs and constraints alongside the financial planning and tax considerations you identify.
We can put together several options and then involve the client for their review and input. If borrowing isn’t suitable, I’ll say so.
Before you reach out
No. The first conversation is about the client’s situation and whether a mortgage review would be useful. A reverse mortgage may be considered, but keeping the current arrangement or pursuing another option may make more sense.
We look at it directly, alongside fees, interest over time and the effect on home equity. We also consider monthly cash flow and the tax implications you identify. Payment relief alone does not prove that an option is better overall.
My focus is mortgage options and borrowing costs. Tax and investment recommendations stay with the client’s qualified advisors. The goal is to bring those perspectives together.
No. Start with a general description and your own contact details. Please don’t send client names, account numbers or financial documents through this form. We can discuss consent and the appropriate next steps before any personal information is shared.
Yes. If you are looking at your own retirement cash flow, you are welcome to get in touch. You can also involve your accountant or financial advisor in the discussion.
Let’s look at the options
Tell me what’s prompting the conversation. We can start there and work out whether a closer look at home equity would be useful.
Sharon Patton
Mortgage Broker
905-334-8729
info@sharonpatton.com
No pressure to recommend a product.
No need to share confidential client details.